Where do your returns come from? Is it an idiosyncratic bet on a particular stock? The idiosyncratic volatility puzzle says you quite literally have the opposite of an edge, you're playing craps at a casino.
Are you harvesting risk premia? VRP, MRP? You are effectively selling insurance. The price you pay for returns during the good times is the drawdown you experience in the bad times. How do your assets covary with the so called stochastic discount factor?
You know how many folks come to me with "if your backtest doesn't beat buy and hold what's the point"? Are you joking? Have you not learned or experienced anything? What does a 30% drawdown feel like when you're managing other people's capital. What do those messages, phone calls, and so on look like? What does redemption look like. The downstream consequences of your choice in risk allocation is what is subject for discussion here, not if the path had arbitrarily worked out.
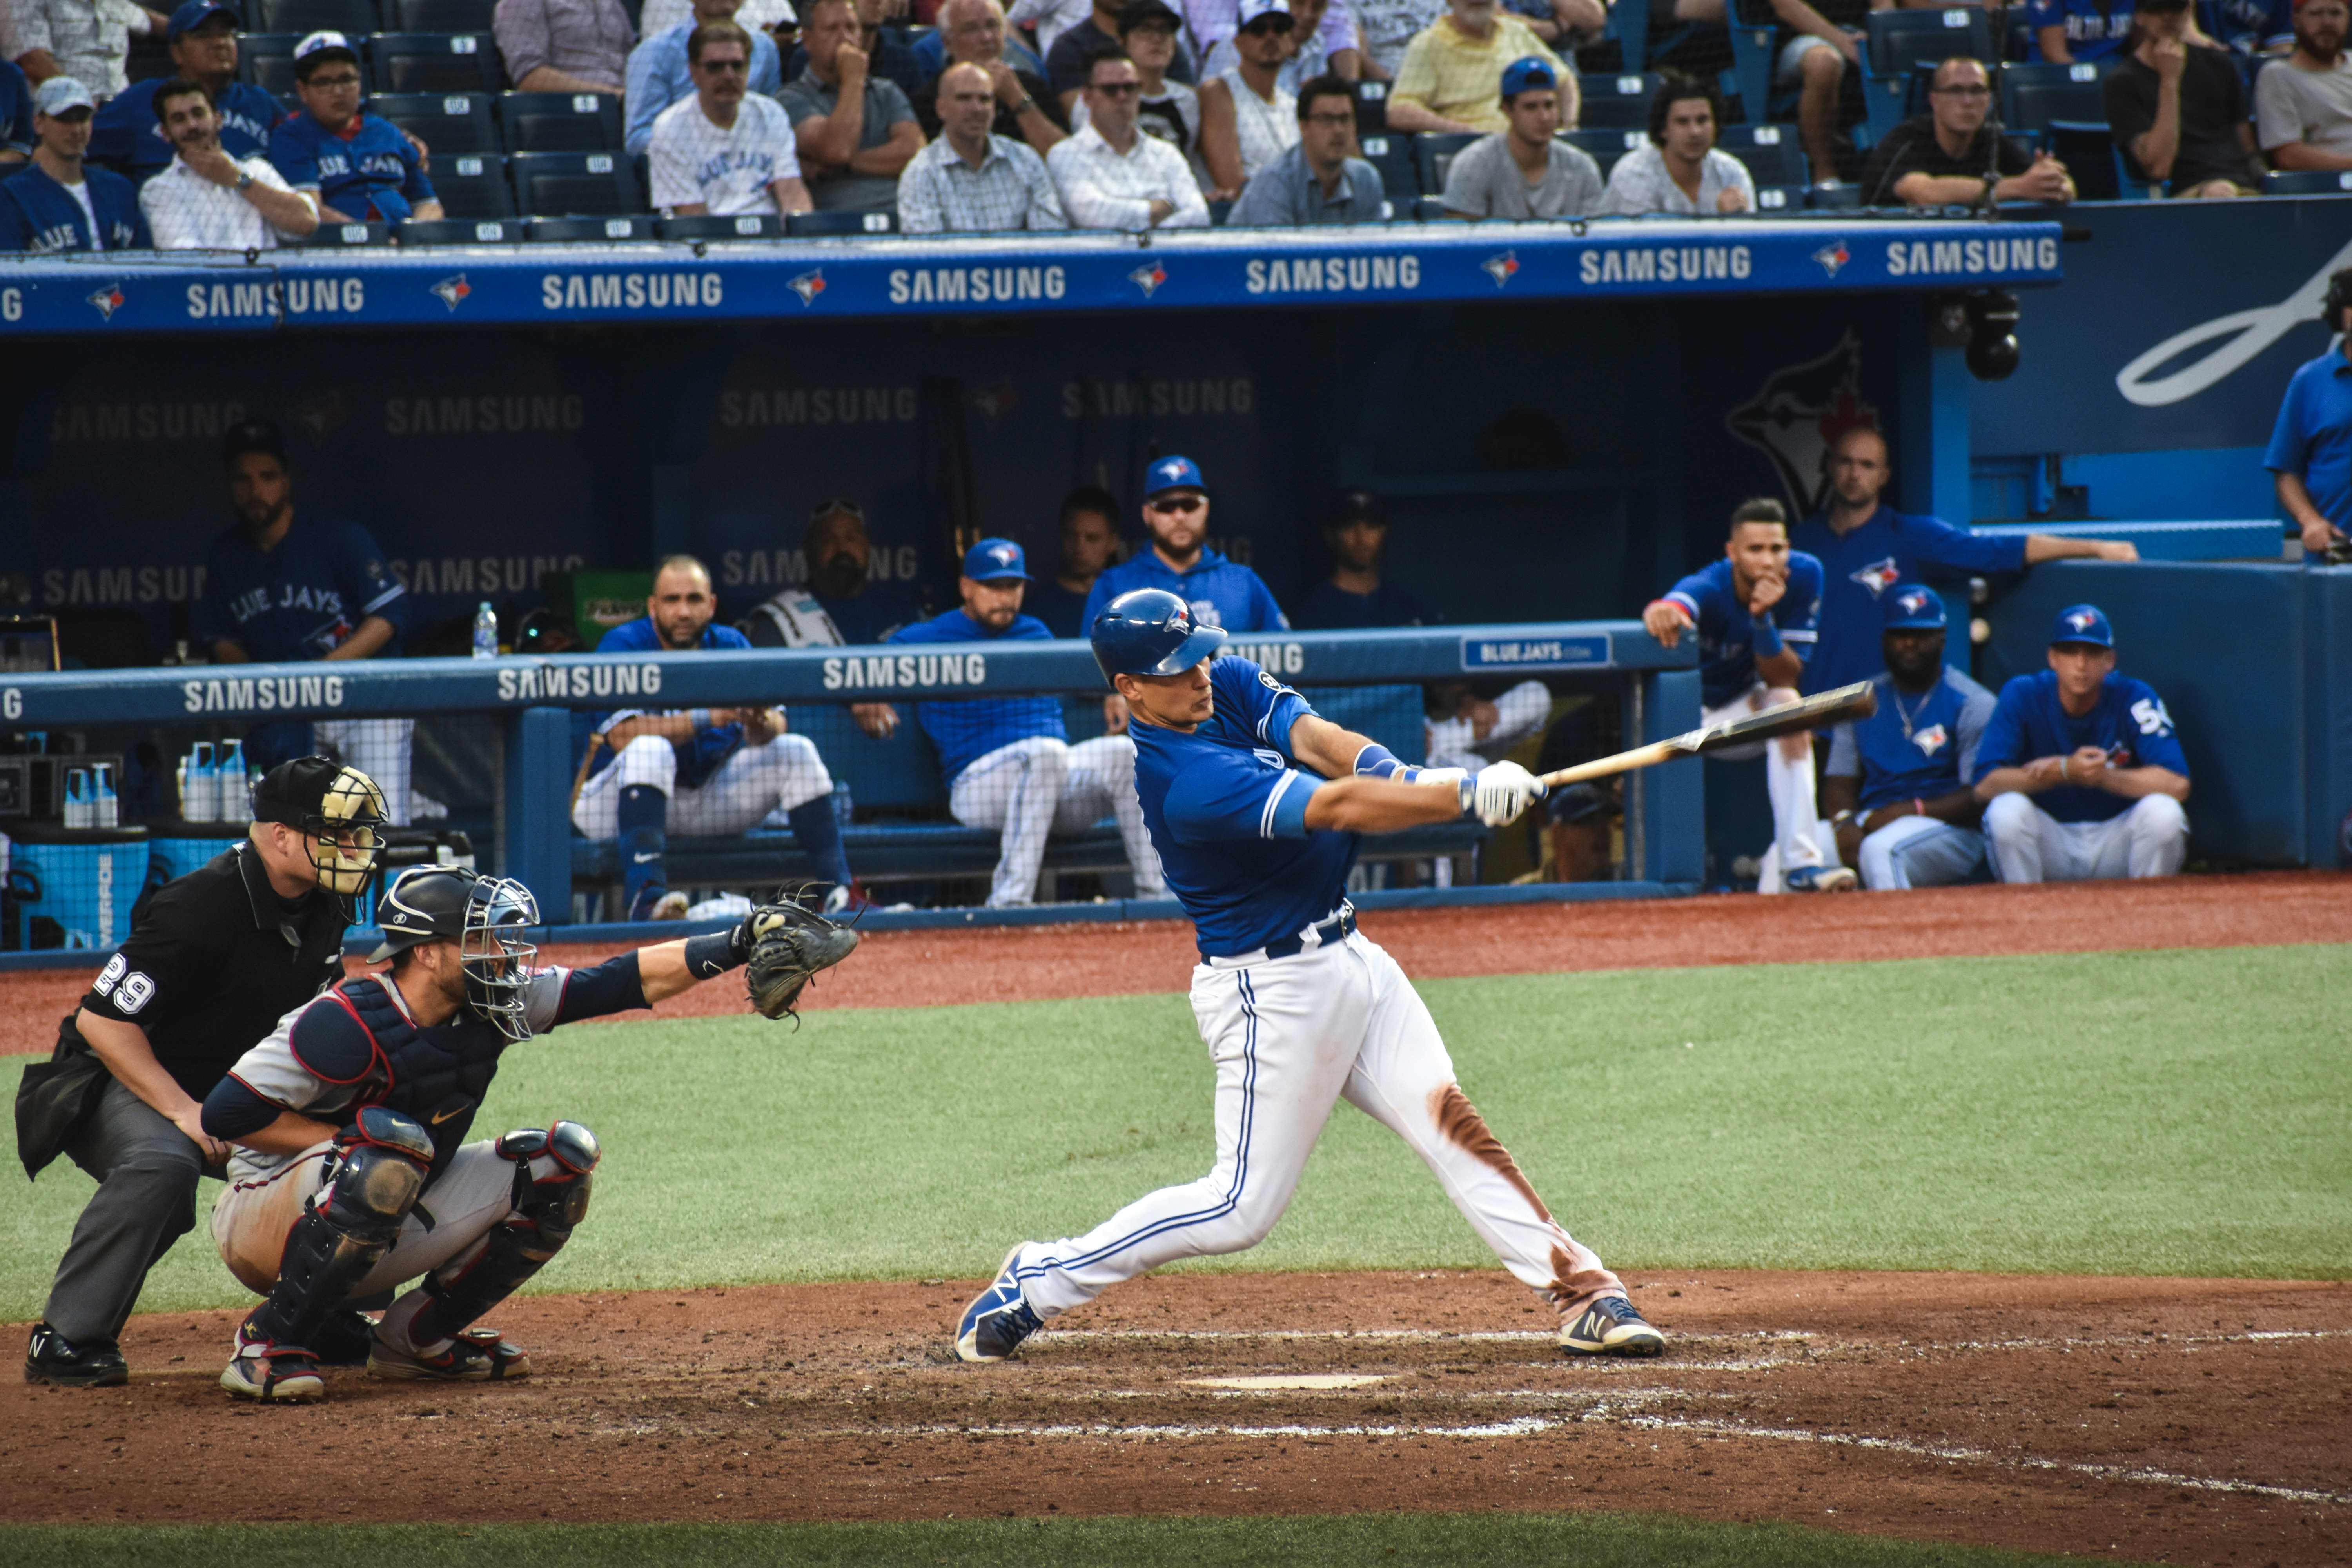
You are swinging at a pitch and are asking me why bother go with a base hit instead of swinging for the fences?
Now how does that sound.
You must swing for base hits so when the fastball down the middle comes around you can knock it out of the park. If you try to swing for the fences all the time you'll be cut way before you can even prove yourself and knock it out of the park. Don't give me any bullshit about alpha decay, smart beta, and so on until you use those ideas to allocate risk. Until you swing at a pitch.
Ironically, I don't like baseball for the same reason I like the markets: it's performance driven. When I was studying the pricing of financial derivatives in college my buddy had a hilarious crash out mid-class deriving risk-neutral densities. "Fuck, fuck. I have to do this shit because I couldn't hit a curveball?"
Funny, mostly harmless, and ironic.
Now the dude doesn't swing with a bat, but with his allocations. He didn't last long in the finance space and has since pivoted.
That's the harsh truth of this space. You will be wrong. Everyone wants to hit a grand slam, but if that's your priority 100% of the time, how will you be in the position to do so when the opportunity actually presents itself?
This fits nicely in the framework we've discussed in previous letters: agents acting with policy functions, Bayesian updating of those policy functions, and weighting potential actions by expected rewards. The idea of swinging for the fences every time falls under the idea of negative EV. It's effectively buying insurance, buying lottery tickets, or anything else that'll bleed you dry looking for a quick hit of convexity. You don't go long volatility all the time, you swing at the right pitch, and that's quite literally where discretionary alpha lies.
It's not an academic exercise, there's nothing certain here. It's a dynamic game. I often illustrate the notion for students with the concept of sports betting. It's unfortunate that the day trading space and degenerate gambling space got a hold of the broader notion of risk management. If I backtest a home run strategy, that doesn't mean it's to work out forward looking. Why?
They just might not hit a home run.
If I make money on average am I extracting a misplacing between what the market expects and what happens? What happens when the market starts overpricing these contracts? No more alpha. We don't have one strategy, we have many strategies. We make independent bets on (hopefully) structurally orthogonal return streams that compound effectively over time. Anything else is taking a massive swing at a pitch and the efficacy is certainly up for discussion.
Bottom of the ninth down by two and need to get on base?
Hit the ball.
Tie game bottom of the ninth, no outs, two men on base? Now we can play with risk in a different way. We can take a bigger swing.
That doesn't mean that it's going to work out.
But you can do more with the risk in the latter than the former. That's the name of the game. If I can pay for convexity with edge earned from another stream I can take a bigger swing. If I can pay for that stream during the bad times with that convexity, I've made progress. This has been and continues to be my approach to risk. Get your base hits. Survive. When you are in the position to swing for the fences, because you can afford it, take a swing.
Can you repeat that process? Well can a batter repeat hitting a home run?
Maybe.
It's a question of performance, not a magical backtest. It remains to be seen.
But it's not amorphous, which is why I love it. You either hit a home run or you don't. You either generate returns or you don't. It doesn't mean you will again, but who else are you going to bet on? The guy that's never hit a home run or Aaron Judge?
In either case, you are allocating risk. There may even be a case to allocate some to the kid that's never hit a home run before. In fact, it goes beyond betting in any capacity, literally everything that is performance driven is an allocation of risk. I think back to the Seahawks Super Bowl loss against the Patriots. There was way too much risk on the books throwing the ball. An interception was unlikely, sure, but in terms of risk management what were you thinking? Give it to Marshawn Lynch, one of the best running backs in the league at the time. Get your base hit. Win the Super Bowl.
We can't do that. That's Annie Duke's concept of resulting, the filtration already played out, we know the outcome. In fact, that is a reasonable bet on a convex outcome with the amount of time left to be played, right? Roman, how is that any different from your convex bet idea? Well, they didn't survive. They bet on a convex outcome with reasonable risk to allocate sure, but you have to weigh it by your survival probability. You have to be ok losing the convex bet. I hold that if they won the Super Bowl on that pass play it still would have been a bad decision and a good outcome. We have to disentangle the two.
I've said for the longest time, you can't fear performance driven outcomes. In fact, if we understand the broader notion of risk and volatility we know the path to progress is a stochastic path with a positive drift. It has to be. If it were up and to the right there would be no reason to do it. The question isn't whether you have performed, or are performing now. The question is can you adapt, evolve, iterate, over time as time demands?
That's what dictates the efficacy of your performance in the long run. Your edge has to be dynamic, you have to keep learning, you have to keep updating. It is the only way to have performed, perform now, and continue to perform in the future. Understanding this, I quite like my odds.
Hope you enjoy my letter.
Be on the lookout for September PCE on Thursday.
Talk more next week.
- Roman

 Roman Paolucci