
 Latest
 Roman Paolucci
The Paolucci Inequality
The Paolucci inequality clearly holds for any policy function, it follows: Action + Iteration > Inaction,
Earlier letters
43 archived letters
2026
35 letters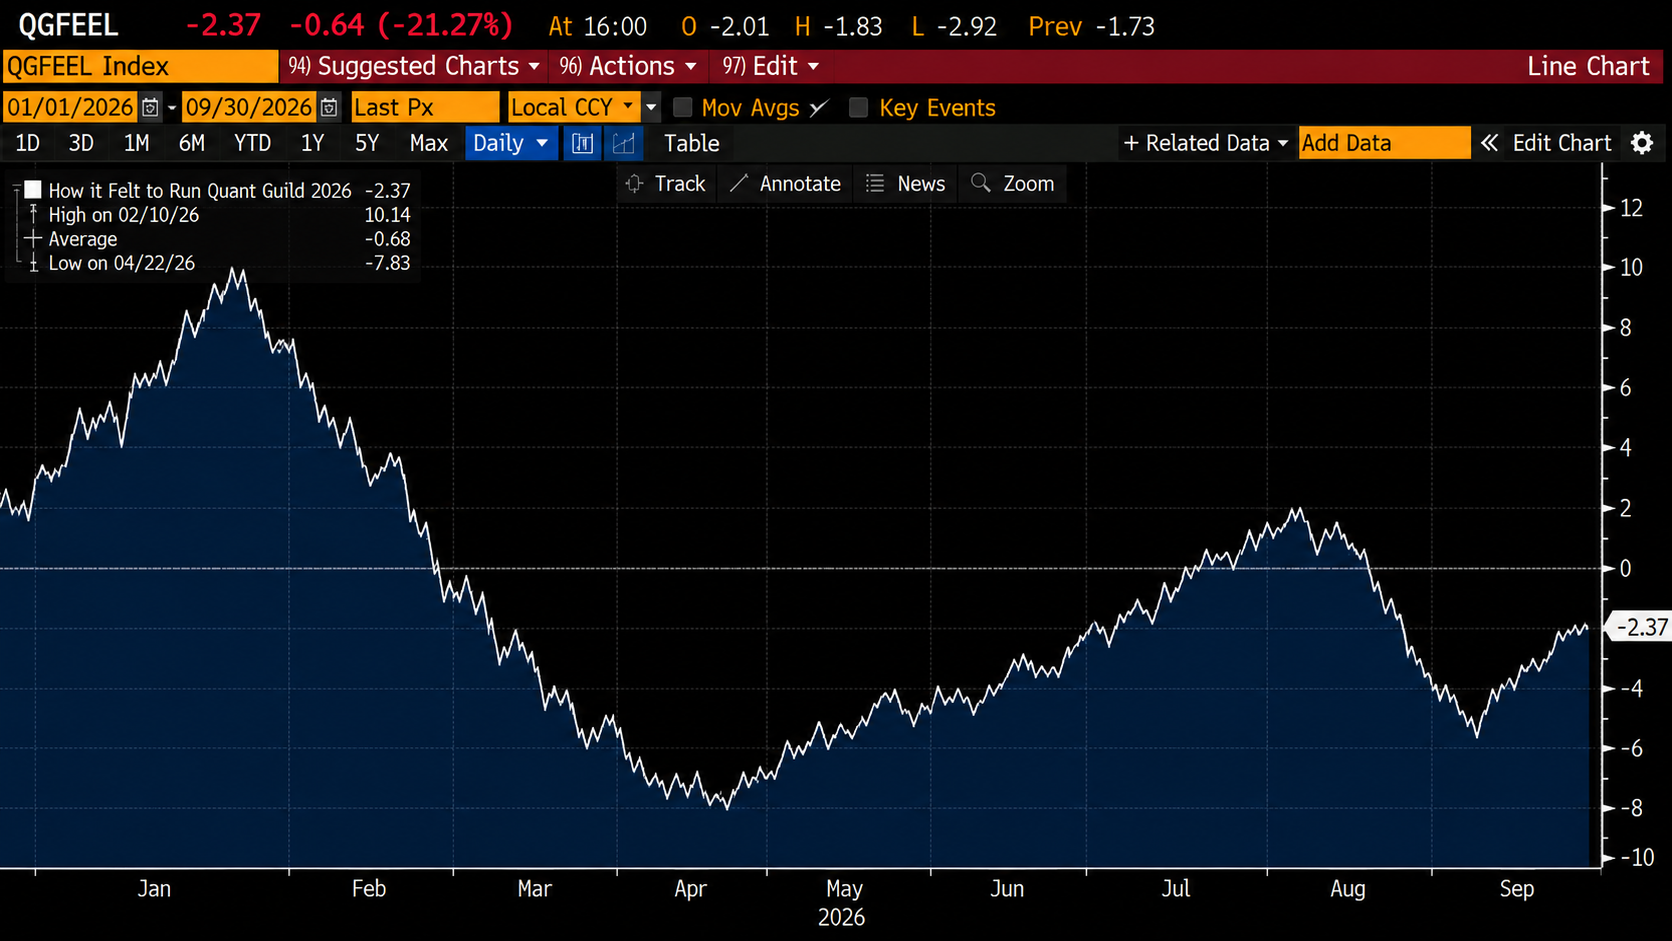 Roman Paolucci
Resilience, Survival, and Convexity
Language is Lossy Compression. A YTD Time Series of My Emotions. Survival is Progress.
 Roman Paolucci
An Arena for Progress
The world is an arena for creative builders, men of action, and keyboard warriors.
 Roman Paolucci
The Discord Extinction Event
To the men in this world that seek to destroy me, and those eager to watch me fall
 Roman Paolucci
On a Train, Passing 100K
A note on 100k subscribers, noise, dreams, fears, and where the train is going next.
 Roman Paolucci
I Was Never Any Good at Poker
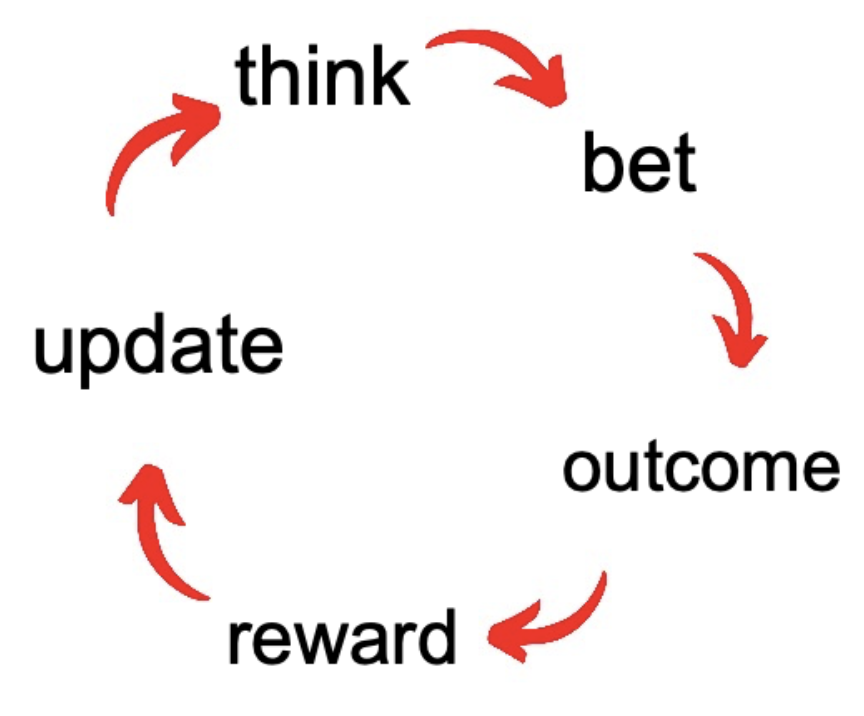
Everything is a bet, including the writing of this letter. But what is the expected reward?
 Roman Paolucci
Outcomes Are Never Enough
Ironically, optimizing for trading PnL is the least effective way to generate wealth.
 Roman Paolucci
Empiricism and Bayesian Updating
Progress is highly non-linear and stochastic. Welcome to the game with rules you create.
 Roman Paolucci
Critics and Cockiness Confidence
Bill Ackman lost $4B, and the media had a field day. But he had something others didn't.
 Roman Paolucci
Acquiring The First Million
Dave Portnoy said it himself, the first million is the hardest, it took him roughly ten years to accumulate that kind of wealth.
 Roman Paolucci
Updating Priors Takes Work
Trading and investing are a lot like Brazilian Jiu-Jitsu and fishing ... actually they're exactly the same.
 Roman Paolucci
The Pokemon Cards in the Attic
I just generated some right tail returns with Pokemon cards.
 Roman Paolucci
Unsolicited Financial Advice
The only thing better than financial advice or judgement is unsolicited financial advice or judgement.
 Roman Paolucci
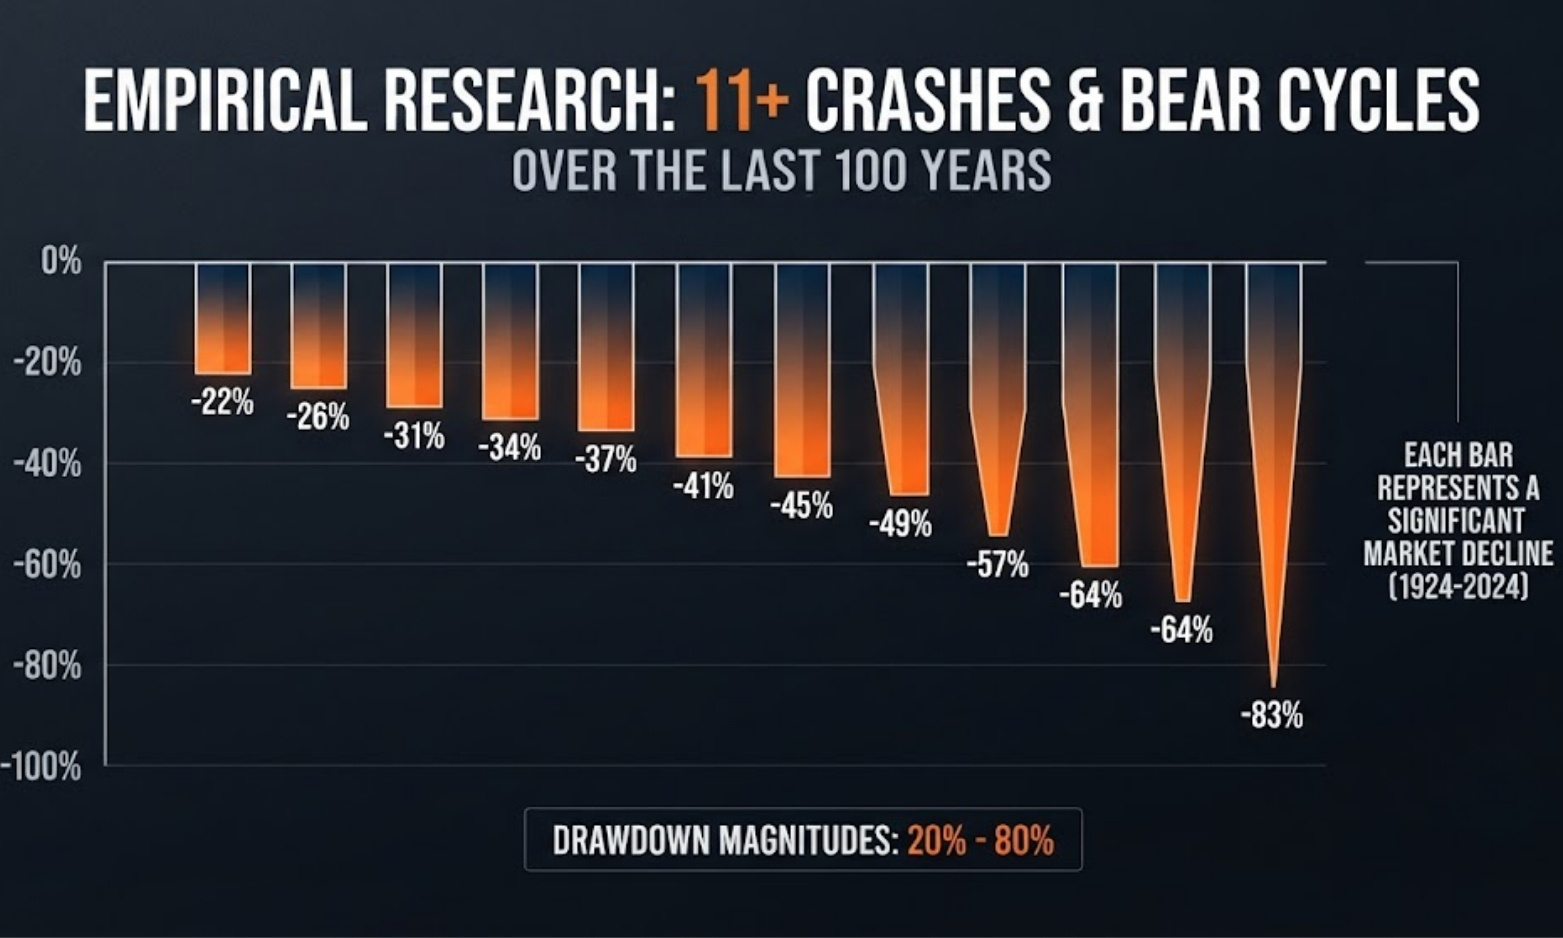
Hedging: Drag or Liquidity?
How many individual investors are asleep at the wheel?
 Roman Paolucci
Bitcoin and Bottom Up Price Discovery
It's time we start talking about Bitcoin, but not in a crypto moonshot capacity, I'm not wired to think like that.
 Roman Paolucci
Dirty Inflated Expectations
Rhetoric, particularly in finance, possesses words that have always troubled me. Primarily the notion of a bubble. These words are a cop-out (of learning the necessary math, probability, and statistics required to understand the amorphous statistical reality of the real world) to fear monger and doomsay.
 Roman Paolucci
The Day Trading Thing
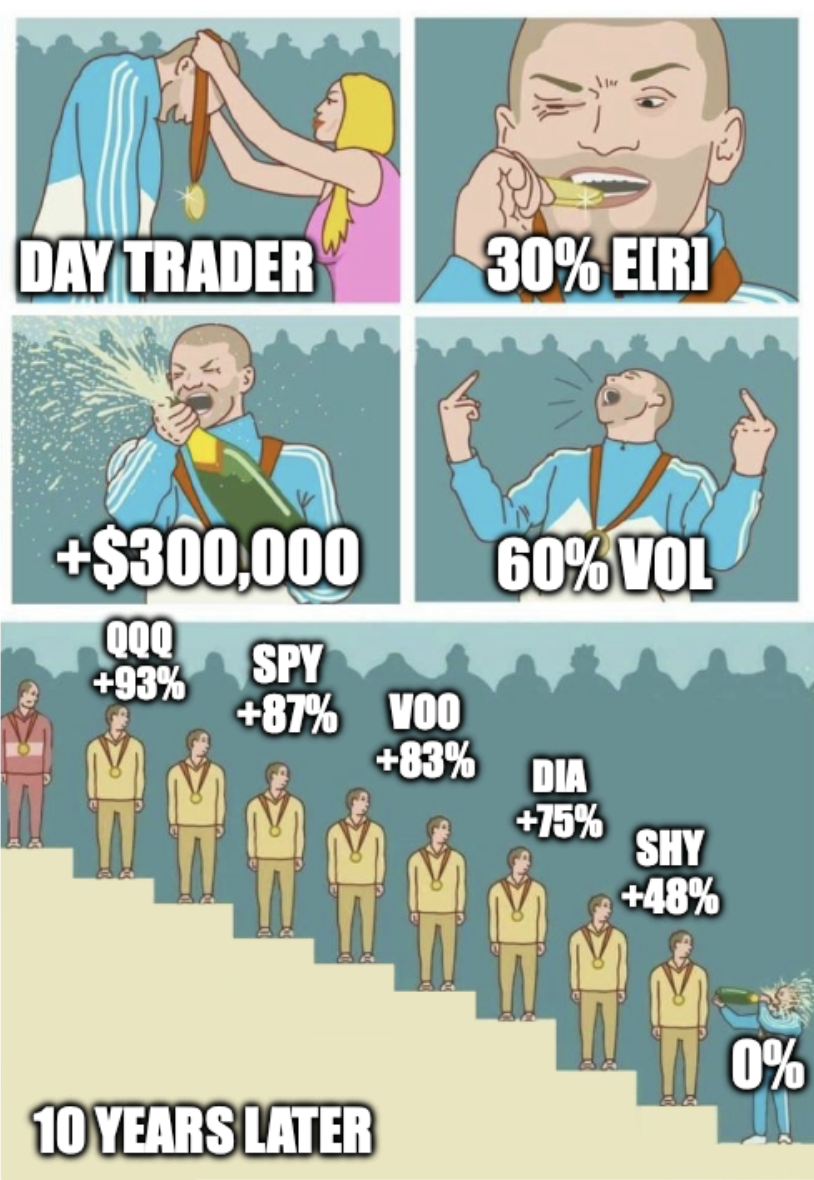
The day trader thing has always been ridiculous to me. Not in the sense that discretionary trading isn't viable, literally all trading is discretionary. Even quantitative trading requires discretion of model and parameter risk.
 Roman Paolucci
Sports Gambling Discretionary Betting
My trade of the week was betting on the Knicks when the odds were heinously priced around the 4th quarter. A strategy (;p) I've used a number of times for everything from football games to MMA fights; useful and only opportunistic (not a trade that gets setup all that frequently, they're the favorite for a reason).
 Roman Paolucci
Monetizing the Leverage Effect
The volatility risk premium, far from a secret, a structure that plenty of institutional funds exploit in the context of generating trading profits. Easier said than done? Absolutely, when are you risk-on, when do you lever up, how much can you lose and will it blow your account? All necessary questions with answers that are ever evolving.
 Roman Paolucci
Banned for Impersonating (Myself)
Well I got banned from YouTube for impersonating myself, that was a fun week. Automations by LLMs (AI) initially created the ban, consistently denied appeals, and kept blaming me for "impersonating Roman Paolucci"...
 Roman Paolucci
To Dot Com Crisis or 08' Crisis
Earnings season for big tech is in full swing and after Intel's stunning performance the waters are choppy in anticipation of setting the level for not only the next set of giants, but likely the trajectory of the markets as traders and investors continue to get numb (as they should) to the global geopolitics.
 Roman Paolucci
Survival and Positive EV
I've been thinking a lot about survival recently and why most people can't shouldn't trade or even manage their own investments. Ephemerally, good decisions are not classified by the quality of the decision making process, but rather the P/L they carry. This couldn't be further from what's required of an active risk taker: to accumulate your statistical edge over time. There are statistical mechanisms to do this.
 Roman Paolucci
The Ignorant Diversify (& That's Ok)
This is your reminder that nobody prices risk correctly. That is not an invitation to blindly trade arbitrarily risky products, rather, an invitation to master your quantitative skills to develop the ability to take advantage of misplaced risk opportunities and/or build concentrated portfolios to scale your wealth.
 Roman Paolucci
Preserving Markovian Dynamics
If everything is path dependent why bother using a model that assumes the structure is Markovian? Non-Markovian models better capture empirical dynamics, though computationally intractable and useless on the desk we ought to use them, right?
 Roman Paolucci
Everything is Non-Stationary
You can't transform the real world into a stationary distribution. In the classroom we are told to produce a distribution using the nth-difference, log returns, the list goes on. But where is time in that distribution? Do you really believe that a two dimensional distribution of returns tells the entire story? That it's just a matter of trivial econometrics or time series analysis to make informed decisions?
 Roman Paolucci
The Role of Wealth Managers
I was long against hiring asset & wealth managers, an opinion I held strongly right out of school and into the first few years of my career as a quant.
 Roman Paolucci
Emotional Algorithmic Trading
Algorithmic trading, systematic trading: "removes the human bias, the emotion from decision making in your edge" says the common man on LinkedIn. Really?
 Roman Paolucci
A Friendly Reminder on Mathematical Models
Models are always wrong, that's not a hot take. I am, however, more critical than most of all forward looking probabilities, statistics, and similar measures.
 Roman Paolucci
Live Class Section: Computational Finance
There are a few seats left for the next live class session on Quant Guild: Computational Finance. This class meets twice a week and prioritizes the quantitative toolkit necessary for advanced coursework in post-graduate academic programs and industrial roles in trading and market-making.
 Roman Paolucci
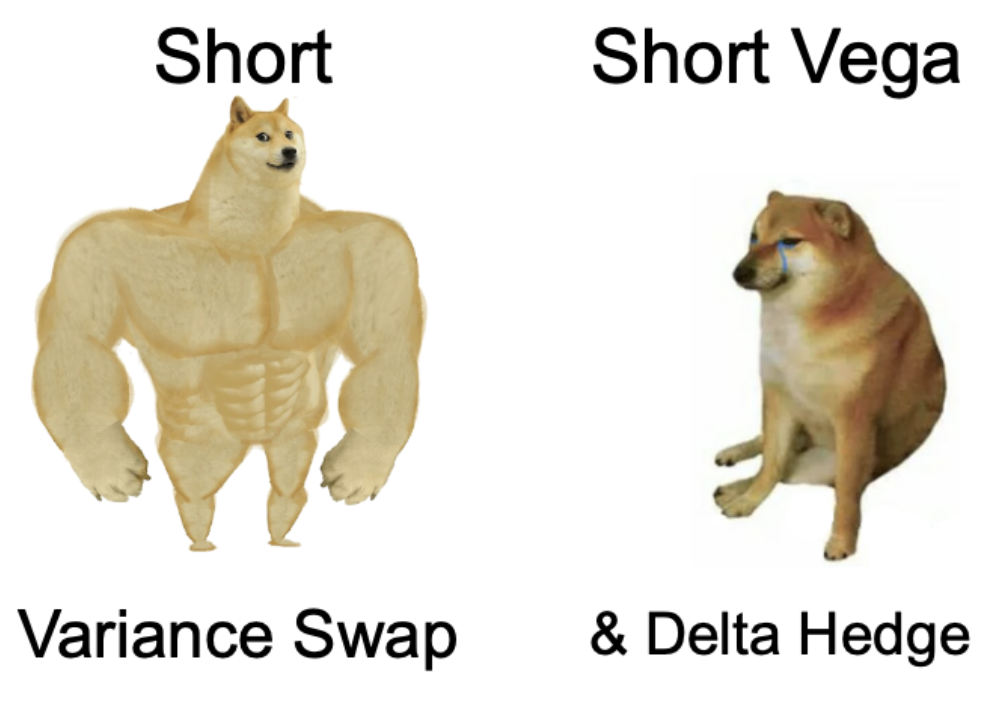
Pricing Variance Swaps
Variance swaps are sick, and thanks to Goldman Sachs, Derman, Carr, Madan, and others, we have an elegant and intuitive understanding of the price under risk-neutral dynamics for a standard diffusion. In fact, the modern VIX is quite literally just the Goldman Sachs / Carr-Madan variance swap model printed on a ticker.
 Roman Paolucci
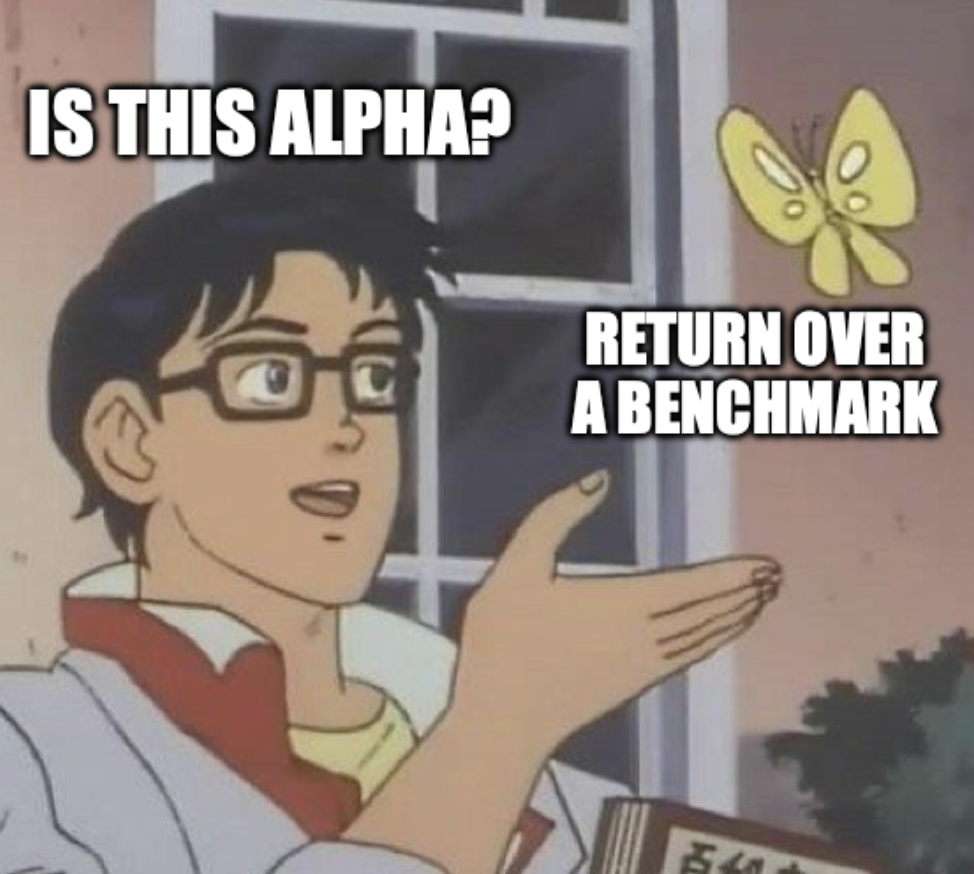
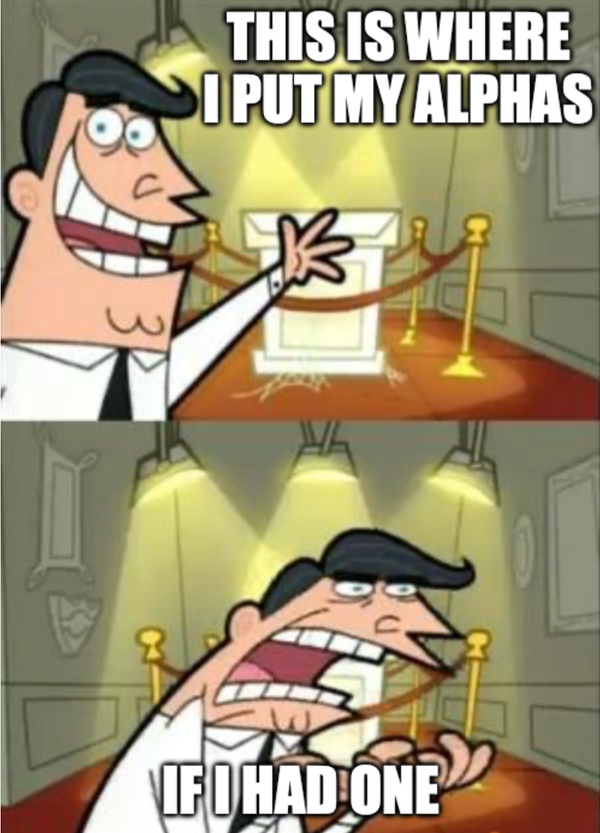
What Exactly is Alpha?
If you survey finance majors in university (which I have recently done) and ask them "what is alpha?" you'll get a variety of interesting responses...
 Roman Paolucci
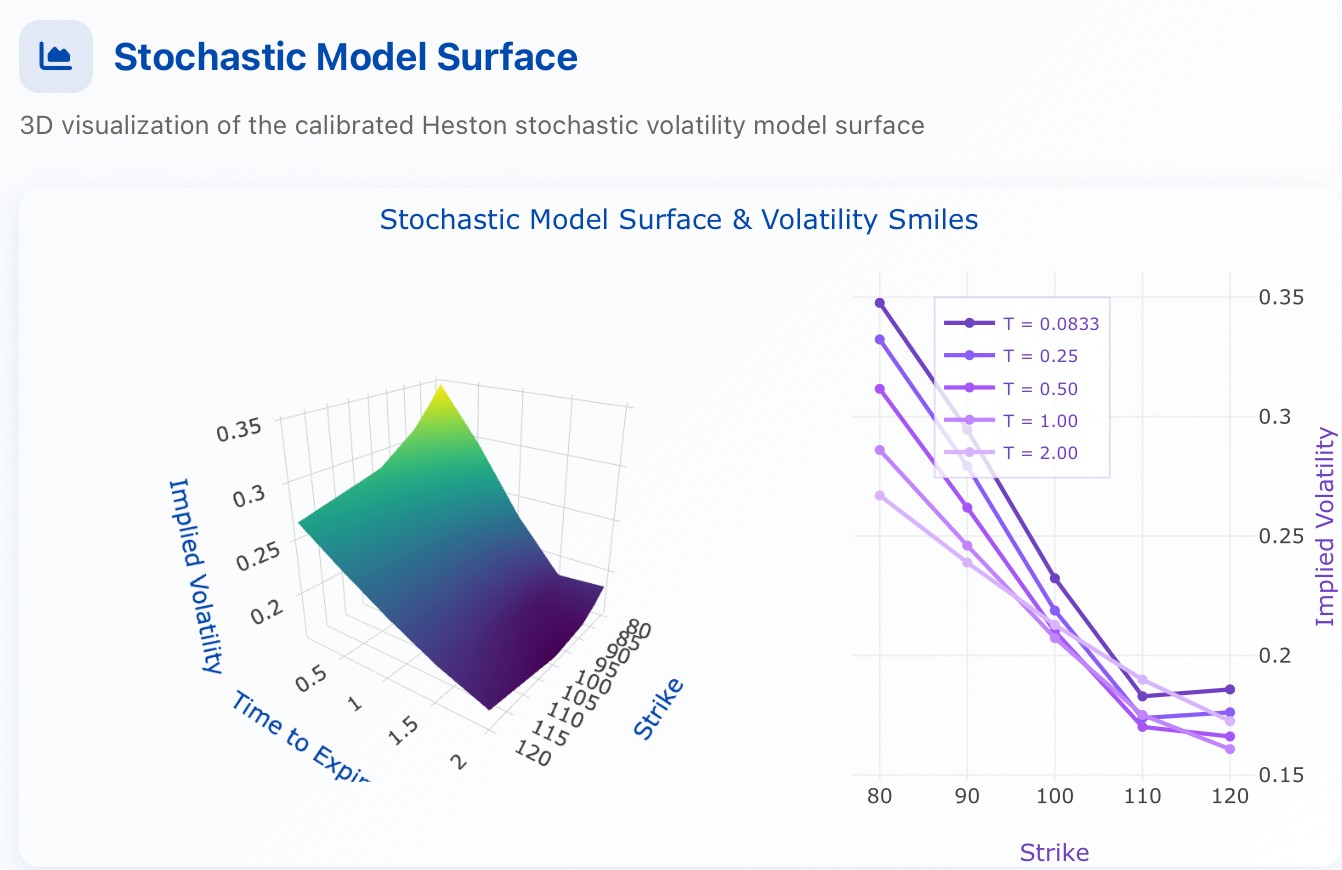
A New Bazaar Item: Stochastic Model Calibration
A new offering has arrived to the Quant Guild Bazaar! Stochastic Model Calibration is available to all Quant Guild Members, or for 15 guild tokens.
 Roman Paolucci
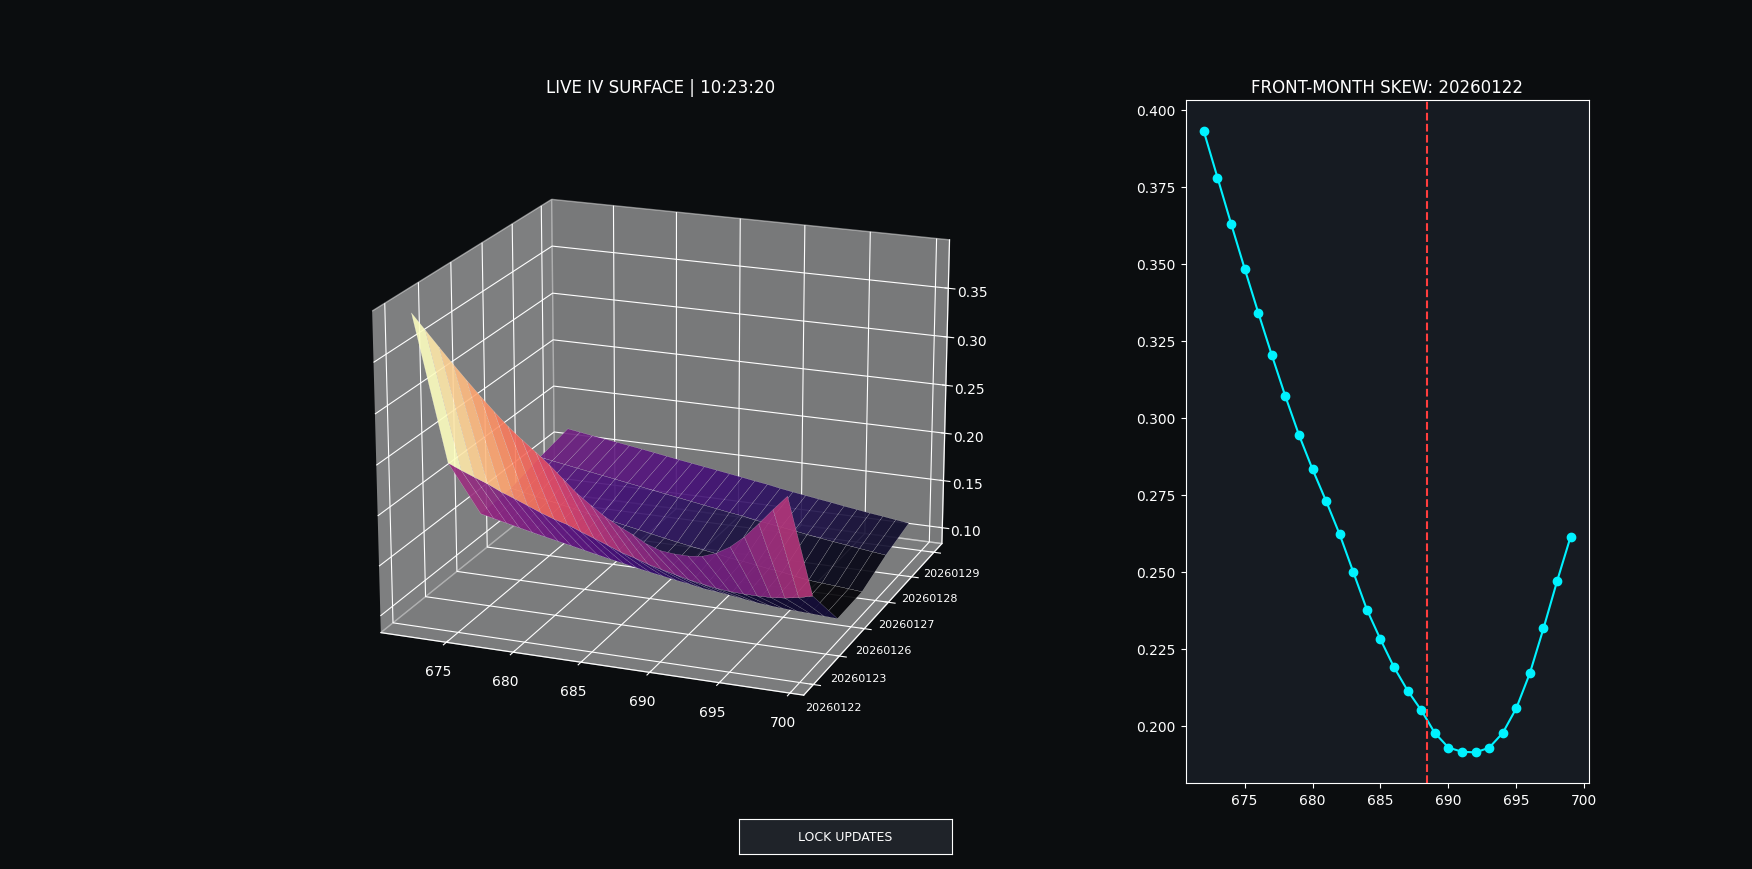
The Implied Volatility Surface
I want to share a note on what I consider to be the most important scientific construct in the trading of financial derivatives: the implied volatility surface. What does it tell us, how is it useful, and how can we access this information in a structured (and algorithmic) way as retailers?
 Roman Paolucci
A New Class: Quant Stats
🚀 I am once again, so beyond stoked to announce a massive update to Quant Guild!
 Roman Paolucci
Beta can be Smart, Very Smart
What is the difference between a portfolio manager or trader with effective timing of exposure to priced risk and a structural inefficient? Is timing exposure (beta) really alpha? In other words, if I know when to increase or decrease my market exposure and I can capitalize on reversion and momentum of that factor is that a strategy that produces alpha? Shouldn't alpha be orthogonal to facets of priced risk?
 Roman Paolucci
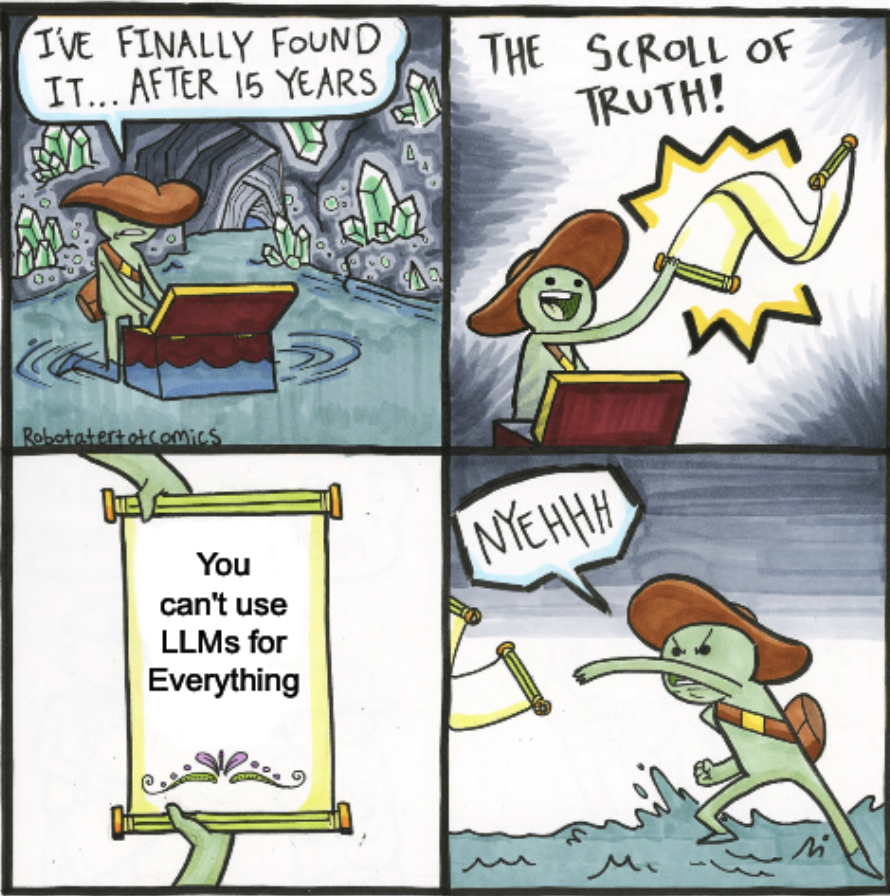
So, Will LLMs Replace Everything?
I'm often asked about the impact of AI in quantitative trading. Large Language Models (LLMs) enable fast ideation and minimum viable products (MVPs), absolutely no doubt about that: quants leveraging artificial intelligence can be 10x more productive. But we suffer the same fate as a calculator, our LLM is really only as smart as our user. If you don't understand how to build what you are intending to (especially in a quant research or trading context) you will be met with an endless series of "You're right! I made a mistake! There is bias in this backtest!" by your LLM.
2025
8 letters Roman Paolucci
Cheers to 2026
It's hard to believe this is the last Weekly Guild Letter of 2025, it's been a crazy year from creating over 75 open-source Quant Guild YouTube videos, building the entire Quant Guild platform from scratch, recording a 20+ hour Python class dedicated to quantitative finance available on Quant Guild, teaching three cohorts of live classes covering financial mathematics and quantitative trading, and of course, building discourses.io from scratch to package my academic and industrial quantitative research for retailers - what a year!
 Roman Paolucci
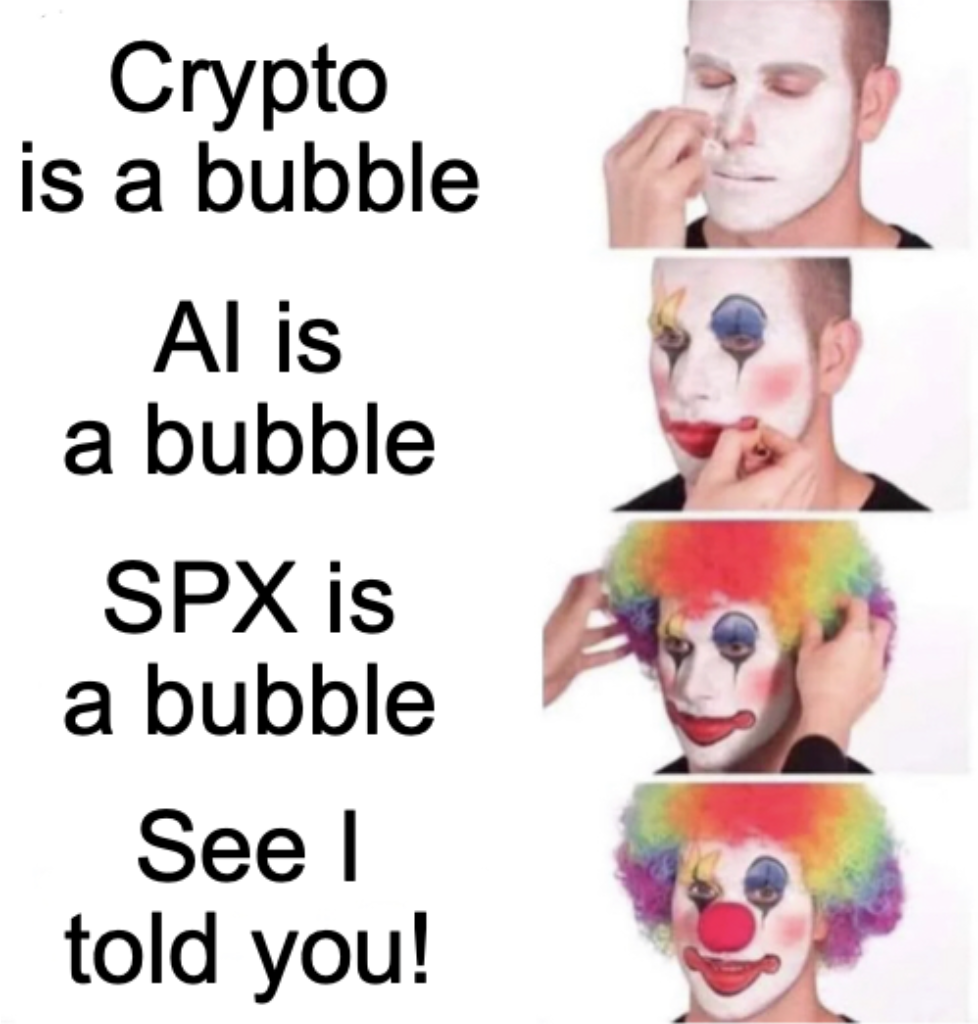
Doomsaying for the Sake of It
I have a friend that traded options for 20 years and he trades now in a purely discretionary capacity. He always says things like "Roman, AI is a crazy bubble, I've seen this before", "Just wait until this AI bubble pops", "I wonder if the US will have a debt crisis before this AI bubble pops". He, along with all of these folks on LinkedIn posting about an impending doomsday, always give me a chuckle. This letter is dedicated to him (don't worry he knows, hey Jay!).
 Roman Paolucci
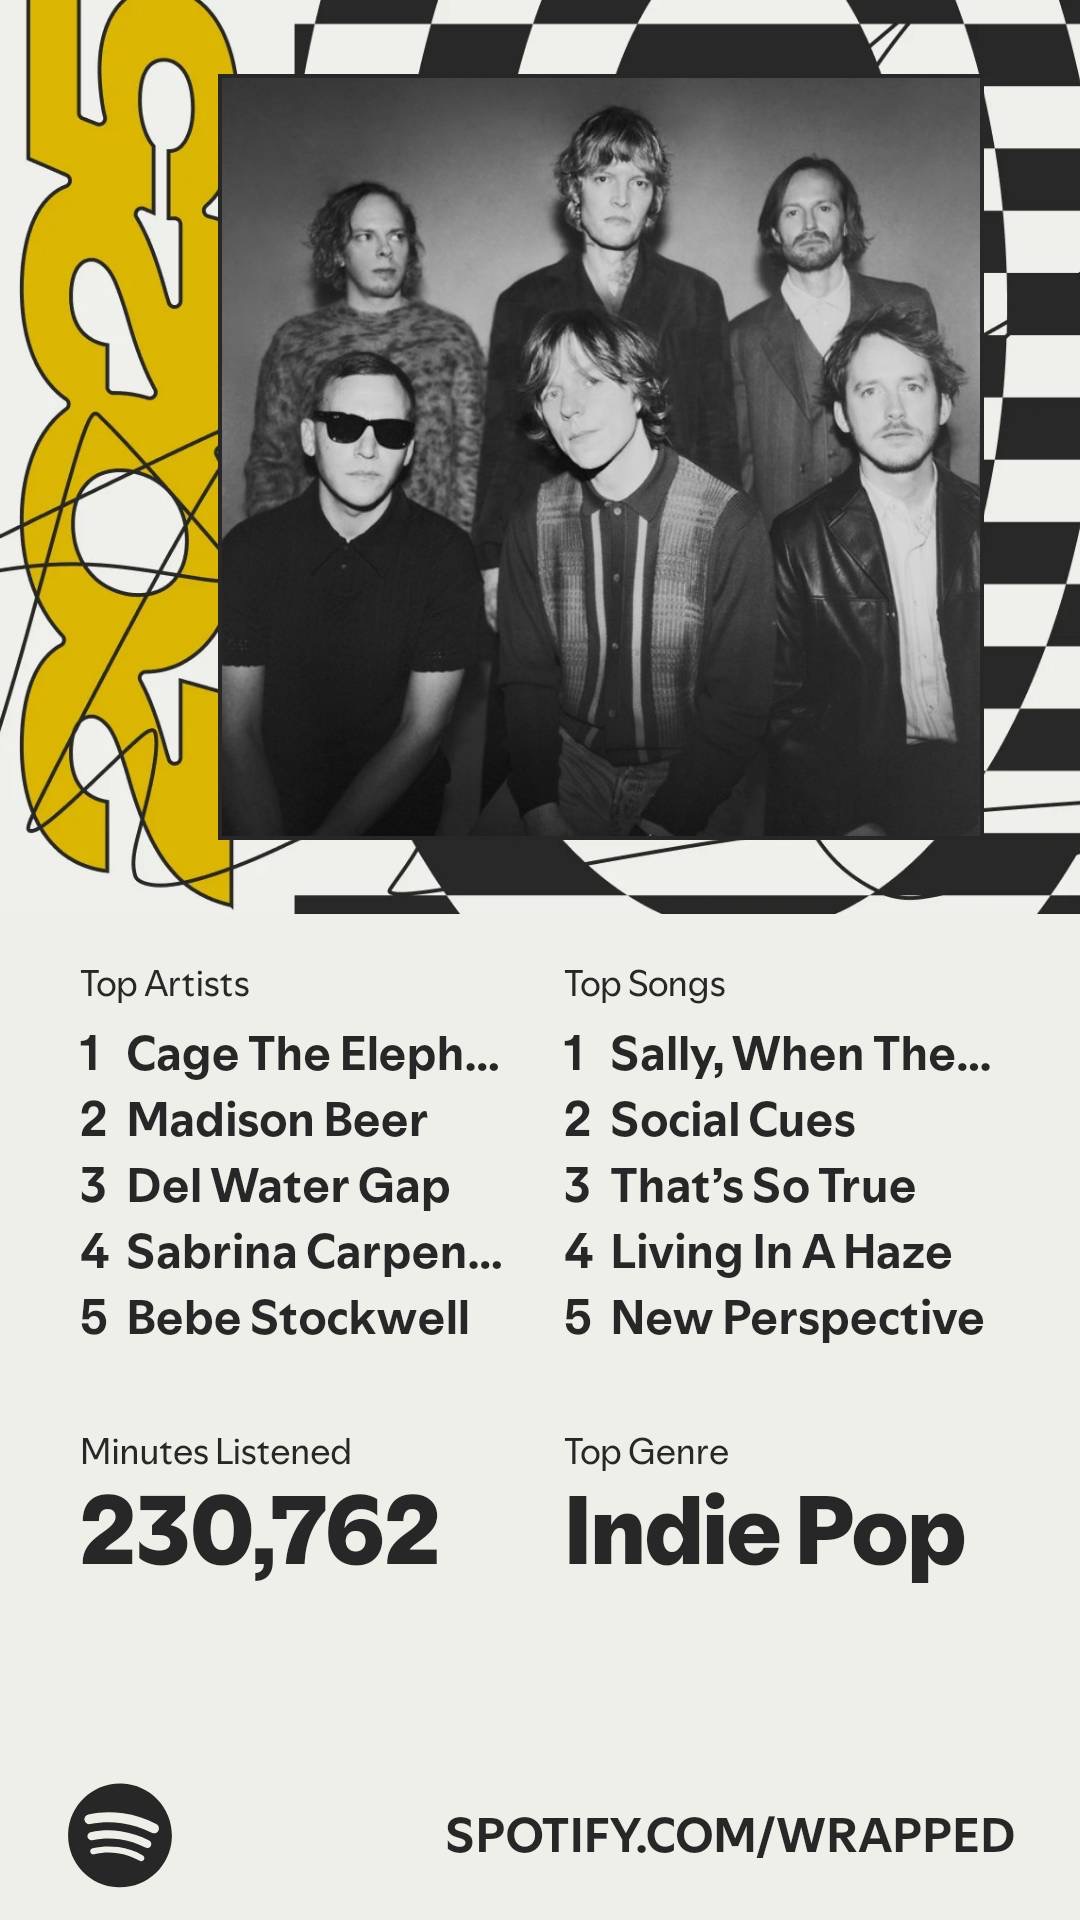
Tis' the Season of Spotify Wrapped (2025)
Well, Spotify wrapped dropped last week so I figured I'd share my top artists and songs that got me through a series of 1 - 4am deployments, bad trades, 6am gym sessions, and of course, accompanied me while I conducted my own research.
 Roman Paolucci
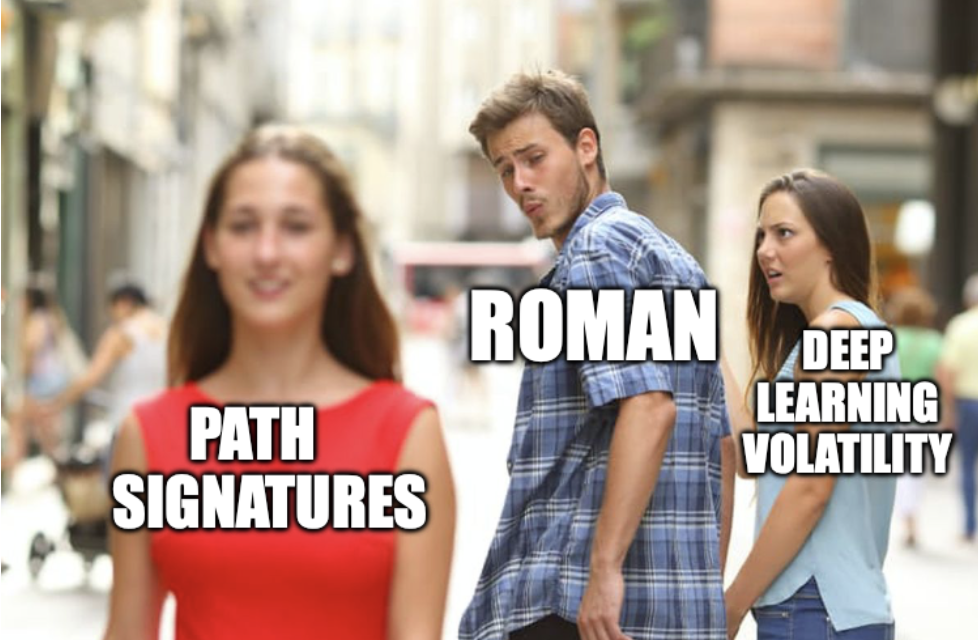
Path Signatures and Rough Path Theory
It would be hard to understate how excited I am about path signatures and rough path theory in general. Instead of trying to put it into words, I created a meme which took my longer to create than a simple Monte Carlo pricing engine. Totally worth it.
 Roman Paolucci
My Desktop Exploded, Nice
You might remember how during my seminar with UCSD's Triton Quantitative Trading I mentioned that my computer needed an upgrade. Well, when I sat down at my desktop the other day I saw a beautiful rainbow, but not outside, it was a pixelated mess on my monitor instead of my code.
 Roman Paolucci
A Quick 5min Adventure, In and Out
Last Thursday evening around 9pm I found time to resolve an issue in one of my systems. Nothing earth shattering, I estimated about 20 minutes to figure out what was going on and 5 minutes of actual coding. If you happened to be active in my Discord that evening between 11pm and 3am you will know this was not the case 😅
 Roman Paolucci
Pricing Autocallable Phoenix Notes
Last week I worked on a series of interesting problems from the efficient simulation of fractional Brownian motion to the development of trading and hedging models for structured products, specifically the 🐦🔥 Autocallable Phoenix Note (sounds so sick, right?). What I've been calling "Quant Guild Season 2" is now in full swing!
 Roman Paolucci
But It Worked On My Machine
It's been quite a week! After a 4am deployment and a few of those good ol' fashioned "But it worked on my machine" I was able to roll out a massive update to Quant Guild - welcome to what I'm calling Quant Guild Season 2.